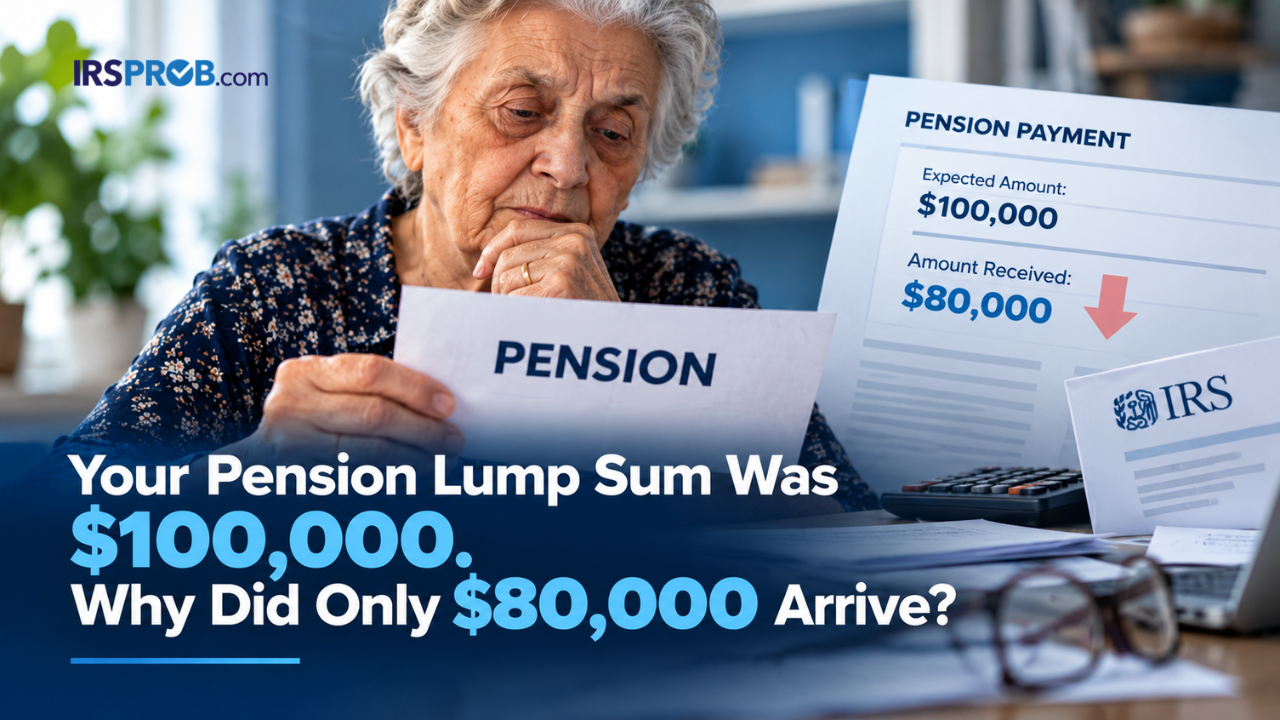
A pension lump sum of $100,000 should mean a $100,000 check. At least, that is what you expected.
Instead, only $80,000 arrived.
The retirement plan withheld $20,000 for federal income tax. You deposited the entire $80,000 into a traditional IRA within 60 days and assumed the rollover was finished.
Then Form 1099-R arrived showing a $100,000 distribution.
The plan may not have made a mistake. When a taxable eligible rollover distribution from an employer retirement plan is paid directly to you, the plan generally must withhold 20%. That withheld money is sent to the IRS, not to your new IRA.
If you want the full $100,000 treated as a rollover, depositing only the $80,000 check may not be enough. You may need to replace the withheld $20,000 using other funds before the 60-day deadline.
Before spending or moving the money, confirm what type of distribution you received, whether it can be rolled over, and when the deadline ends.
- Why Your Pension Lump Sum Was Reduced by 20%
- The $100,000 Pension Lump-Sum Example
- Withholding Is Not Your Final Tax
- Direct Rollover Versus a Check Paid to You
- When Does the 60-Day Clock Begin?
- Not Every Distribution Can Be Rolled Over
- Employer Plans and IRAs Can Follow Different Rules
- What Form 1099-R May Show
- Could the Additional 10% Tax Apply?
- What if the Pension Lump Sum Check Just Arrived?
- What if the 60-Day Deadline Passed?
- Other Effects of a Taxable Distribution
- What to Do Next
- Frequently Asked Questions
Why Your Pension Lump Sum Was Reduced by 20%
Most taxable eligible rollover distributions from employer retirement plans are subject to mandatory federal withholding when paid directly to the participant.
The withholding rate is generally 20% of the taxable amount.
The rule can apply even if you plan to deposit the money into an IRA a few days later. Your intention does not turn the payment into a direct rollover.
The important question is how the payment was made.
If the plan sends the funds directly to an eligible retirement plan or IRA, the transaction may qualify as a direct rollover. A check made payable to the receiving custodian for your benefit can also qualify, even if the check is mailed to you for delivery.
Federal tax generally is not withheld from the amount directly rolled over.
If the check is payable to you personally, the employer plan generally must withhold 20% from the taxable eligible rollover distribution.
It may have been sent to the IRS as federal income tax withheld under your name.
The $100,000 Pension Lump-Sum Example
Assume the entire $100,000 is a taxable eligible rollover distribution from your employer retirement plan.
You ask for the payment personally instead of arranging a direct rollover.
The Numbers
- Gross distribution: $100,000
- Federal income tax withheld: $20,000
- Check paid to you: $80,000
- Amount deposited into a traditional IRA: $80,000
- Amount not rolled over: $20,000
If the $80,000 deposit satisfies the rollover rules, that portion may qualify as a nontaxable rollover.
The remaining $20,000 may be treated as a taxable distribution because it was not deposited into the receiving retirement account.
If you want the entire $100,000 treated as rolled over, you generally must contribute the $80,000 received plus another $20,000 from other available funds within the permitted period.
The $20,000 originally withheld is generally claimed as federal income tax paid when you file your return. Depending on your complete tax situation, it may reduce your balance or increase your refund.
This example assumes the pretax distribution is rolled into a traditional IRA or another eligible pretax retirement plan. A rollover of pretax money to a Roth IRA is generally taxable in the year of the rollover.
Withholding Is Not Your Final Tax
The 20% withheld is a tax payment. It is not a final calculation of the tax owed.
If the full distribution qualifies as a rollover to a traditional IRA or another eligible pretax plan, the rollover itself may not create current taxable income. The withholding can still be reported as a tax payment.
If part of the distribution is not rolled over, that part may be taxable. Your final result depends on total income, filing status, deductions, credits, tax bracket, and other facts.
The 20% withholding may be more or less than your final tax.
That is why “the plan already took out the tax” does not settle the issue. Withholding is a payment toward the return. The return determines the actual result.
Direct Rollover Versus a Check Paid to You
The words used in retirement paperwork can sound similar, but the payment method matters.
Direct Rollover
In a direct rollover, the employer plan sends the funds directly to another eligible retirement plan or IRA.
The plan may also issue a check that is delivered to you but made payable to the receiving custodian for your benefit. That may still qualify as a direct rollover because the check is not payable to you personally.
A direct rollover generally avoids mandatory withholding. It also reduces the risk of missing a deadline or spending part of the distribution.
60-Day Rollover
In a 60-day rollover, the plan pays the distribution directly to you.
You then deposit all or part of the eligible distribution into another eligible plan or IRA within 60 days.
Because the payment was made to you, the employer plan generally withholds 20%. If you want to roll over the gross amount, you usually need to replace the withholding from another source.
The IRS explains these choices in its retirement-plan rollover guidance .
When Does the 60-Day Clock Begin?
The 60-day period generally starts when you receive the distribution.
Do not assume it begins when you deposit the check, contact the IRA company, or finish the account paperwork.
Find the actual date the payment was received. Keep the envelope, check copy, plan statement, bank record, and delivery confirmation.
Waiting until the last few days can create problems. The receiving institution may need time to open the account, review the deposit, or correct how it was coded.
Tell the institution that the deposit is a rollover. Keep confirmation showing the amount, deposit date, and type of contribution recorded.
Not Every Distribution Can Be Rolled Over
The 60-day rule does not make every retirement payment eligible for rollover.
Payments that generally cannot be rolled over include:
- Required minimum distributions
- Hardship distributions
- Certain substantially equal periodic payments
- Certain corrective distributions
- Some other payments excluded by law
Confirm eligibility before replacing withholding or depositing the money.
If part of a distribution is an RMD, that portion generally cannot be rolled over. Depositing an ineligible amount into an IRA could create an excess contribution rather than a valid rollover.
Employer Plans and IRAs Can Follow Different Rules
The mandatory 20% rule generally applies to taxable eligible rollover distributions paid directly to you from employer retirement plans.
That does not mean every IRA distribution has the same mandatory withholding.
IRA distributions generally follow different withholding rules. Depending on the circumstances, a taxpayer may be able to elect a different percentage or no withholding.
Form W-4R is used for certain nonperiodic payments and eligible rollover distributions. Form W-4P generally applies to periodic pension or annuity payments.
Before assuming the payer used the wrong percentage, confirm the account and payment type.
What Form 1099-R May Show
For the $100,000 example, Form 1099-R may report:
- $100,000 as the gross distribution
- A taxable amount or an indication that it was not determined
- A distribution code
- $20,000 of federal income tax withheld
The gross distribution can be $100,000 even though you received only $80,000 in cash. The withheld amount was paid to the IRS on your behalf.
Form 1099-R may not show whether you later completed a valid 60-day rollover. Your return and supporting records report that result.
Do not assume the form is wrong because the gross amount exceeds the check. A corrected form may be needed if the payer reported the underlying transaction incorrectly, but not merely because you later completed a rollover.
Could the Additional 10% Tax Apply?
If part of the distribution remains taxable, an additional 10% tax may apply when the taxpayer is under age 59½.
It does not apply in every situation. Exceptions depend on the person’s age, plan type, reason for the payment, separation date, and other facts.
For many qualified employer plans, one exception can apply when you separate from service during or after the calendar year in which you reach age 55. Different rules can apply to certain public safety employees and firefighters.
The separation-from-service exception generally does not carry over to an IRA. Moving the money to an IRA and later withdrawing it can therefore produce a different result.
Retirement by itself does not automatically create an exception.
What if the Pension Lump Sum Check Just Arrived?
Start with the paperwork, not the money.
- Confirm the gross distribution.
- Confirm the federal withholding.
- Identify the retirement-plan type.
- Ask whether the payment is eligible for rollover.
- Find the date you received it.
- Calculate the final day of the 60-day period.
- Contact the receiving plan or IRA custodian.
- Confirm that the account can accept the rollover.
- Decide whether you can replace the withheld amount.
- Keep proof of the completed deposit.
Do not spend the check while deciding.
If you cannot replace the withheld amount, a partial rollover may still be possible. The amount not rolled over may be taxable, but that does not automatically make the entire distribution taxable.
What if the 60-Day Deadline Passed?
Do not assume the problem is automatically fixed or that relief is impossible.
The IRS may waive the 60-day requirement in certain circumstances. Relief may be available through an automatic waiver, self-certification, or a private letter ruling.
Each option has requirements.
For self-certification, the late rollover generally must be completed as soon as practical after the reason for the delay ends. IRS guidance says completion within 30 days will ordinarily satisfy that timing requirement.
Self-certification is not final IRS approval. The IRS may later review whether the requirements were met.
A private letter ruling can involve professional fees and an IRS user fee, so it will not be practical in every case.
Document what caused the delay, when the problem ended, when it was discovered, and what steps you took afterward.
Other Effects of a Taxable Distribution
A taxable pension distribution can affect more than the tax on that payment.
Additional income may:
- Increase the taxable portion of Social Security
- Raise adjusted gross income
- Reduce income-based deductions or credits
- Increase state income tax
- Push income into a higher tax bracket
- Affect future Medicare Part B or Part D premiums
Medicare’s income-related monthly adjustment amount generally uses tax-return income from two years earlier. A taxable distribution this year may therefore affect Medicare premiums in a later year.
IRSProb explains how retirement income can affect Medicare premiums .
What to Do Next
If you have not requested the payment, ask whether a direct rollover is available. Confirm exactly how any check will be written.
If the check arrived and the deadline is still open, identify the gross amount, withholding, eligibility, receiving account, and final rollover date immediately.
If the deadline passed, obtain professional advice before treating the distribution as fully taxable or assuming self-certification solves it.
If Form 1099-R arrived, compare it with the plan statement and rollover confirmation.
If the IRS sends a notice, identify the tax year, distribution, proposed change, and response deadline. Gather proof of the rollover before responding. IRSProb explains what to check when an IRS notice arrives .
Received a pension check with 20% missing?
Review the gross distribution, withholding, rollover eligibility, receiving account, and 60-day deadline before deciding what to do with the money.
Review IRS Rollover GuidanceFrequently Asked Questions
Why did my plan withhold exactly 20%?
Most taxable eligible rollover distributions from employer plans paid directly to the participant are subject to mandatory 20% federal withholding.
Is the withheld money lost?
No. It generally becomes federal income tax paid under your name. It is not automatically placed into your new retirement account.
Can I roll over only the check I received?
Yes, a partial rollover may qualify. The eligible amount not rolled over may be taxable.
Can I replace the withheld 20%?
Generally, yes. If the full eligible distribution is deposited within the permitted period, the entire amount may qualify as rolled over.
Can I roll over an RMD?
Generally, no. A required minimum distribution is not an eligible rollover distribution.
Will I receive credit for the withholding?
Generally, yes. Properly reported federal withholding is claimed as a tax payment on the return.
Can the IRS waive a missed deadline?
Possibly. Relief depends on the facts and applicable requirements. It is not automatic.
Final Takeaway
A $100,000 pension lump sum can produce an $80,000 check without the plan making an error.
The missing $20,000 may have gone to the IRS as mandatory withholding. If you want the entire eligible distribution treated as a rollover, you may need to replace that amount and complete the rollover on time.
A direct rollover can often avoid this problem. If the check is already in your hands, review the paperwork before the clock runs out.