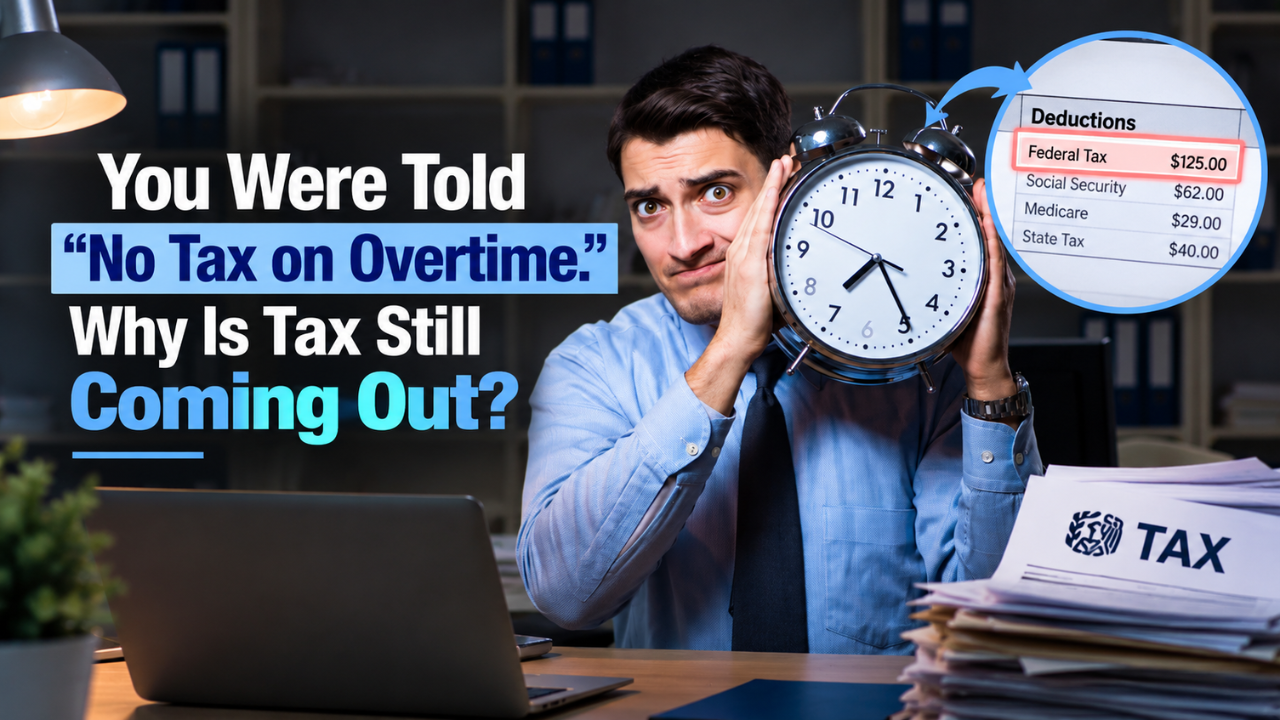
You worked extra shifts after hearing that overtime was now tax-free.
Then your paycheck arrived.
Federal income tax was still withheld. Social Security and Medicare taxes were still there too. You may have wondered whether payroll missed the new law.
The paycheck may be correct.
“No Tax on Overtime” is the common name for a federal income tax deduction. It does not mean every overtime dollar is tax-free or that all taxes must disappear from each paycheck.
The deduction generally applies only to qualified overtime compensation above your regular rate of pay. You normally claim it on your federal return, and Social Security and Medicare taxes can still apply.
That distinction matters.
Before changing Form W-4 or challenging payroll, check which part of your overtime may qualify, whether the federal overtime rules apply to your job, and what your employer reports on Form W-2.
- Your Paycheck May Not Be Wrong
- What “No Tax on Overtime” Actually Means
- Only the Overtime Premium May Qualify
- Why Federal Income Tax Is Still Withheld
- Social Security and Medicare Taxes Still Apply
- Not Every Payment Called Overtime Qualifies
- The Federal Overtime Rules Matter
- Where Qualified Overtime Appears on Form W-2
- Should You Change Form W-4?
- What to Do if the Reported Amount Looks Wrong
- What Matters Most
- Frequently Asked Questions
Your Paycheck May Not Be Wrong
Tax withholding is not your final tax calculation.
Your employer withholds federal income tax during the year using your wages, pay schedule, Form W-4, and IRS withholding rules. When you file your return, your income, deductions, credits, payments, and filing status come together to determine the final result.
The overtime deduction can lower federal taxable income on that return. It does not automatically remove overtime from every payroll calculation.
That means federal income tax may still come out of an overtime check. You may receive the benefit later when you file, or you may account for an expected deduction through a properly completed Form W-4.
Do not assume that withholding is money lost forever. Also, do not assume every dollar withheld will come back as a refund. Your entire tax return controls the final result.
What “No Tax on Overtime” Actually Means
The deduction applies for tax years 2025 through 2028. Eligible taxpayers may claim it whether they take the standard deduction or itemize.
The maximum deduction is generally $12,500 on an individual return or $25,000 on a joint return.
It begins to phase out when modified adjusted gross income exceeds $150,000, or $300,000 for joint filers.
The taxpayer receiving the qualified overtime compensation must have a Social Security number valid for employment and meet the applicable reporting requirements.
The number generally must be issued by the return's due date, including extensions. A married taxpayer generally must file jointly to claim the deduction.
It is not an exclusion that makes all overtime disappear from gross wages.
IRSProb has a broader guide explaining how the No Tax on Overtime deduction works . Here, the focus is the question workers see on payday: why are taxes still coming out?
Only the Overtime Premium May Qualify
Qualified overtime compensation generally means the portion paid above the worker’s regular rate that is required by section 7 of the Fair Labor Standards Act.
For ordinary time-and-a-half pay, that is usually the extra “half,” not the whole payment for the overtime hour.
A Simple Time-and-a-Half Example
Suppose your regular rate is $20 per hour. For a qualifying overtime hour, you receive $30.
- The first $20 represents your regular-rate pay.
- The additional $10 represents the overtime premium.
- The potential qualified overtime amount is generally $10, not $30.
If you work ten qualifying overtime hours, you receive $300 in total overtime-hour pay. In this simplified example, $100 may represent qualified overtime compensation.
The Department of Labor guidance on the regular rate explains the basic federal time-and-a-half rule.
Real payroll can be more complicated. Bonuses, multiple rates, piecework, shift premiums, special schedules, and public-sector rules can affect the regular rate and overtime calculation.
Do not force every pay stub into this simple example.
Why Federal Income Tax Is Still Withheld
The IRS says qualified overtime generally remains wages for federal income tax withholding.
An employer may not simply remove withholding because an employee expects to claim the deduction.
For 2026, an employer may account for the expected deduction if the employee gives the employer an updated and valid Form W-4. The employer then follows the federal withholding procedures.
That does not mean everyone earning overtime should rush to submit a new W-4.
If you reduce withholding too much, the return may show a balance due.
Your spouse’s wages, a second job, contract work, investment income, bonuses, and other tax items may matter. Overtime is only one part of the picture.
Social Security and Medicare Taxes Still Apply
The overtime deduction is an income tax deduction.
Qualified overtime generally remains subject to Social Security and Medicare taxes.
That is why a pay stub may still show:
- Social Security tax
- Medicare tax
- Additional Medicare Tax when applicable
- Federal income tax withholding
The overtime may also remain subject to federal unemployment tax on the employer’s side.
State income-tax treatment can differ because a federal deduction does not automatically change state law.
Even when the deduction lowers federal taxable income, Social Security and Medicare taxes generally remain.
Not Every Payment Called Overtime Qualifies
Employers may use the word “overtime” for several kinds of extra pay.
The label on a pay stub does not settle whether the federal deduction applies.
Company-Policy Overtime
An employer may voluntarily pay time and a half after eight hours in a day, for weekend work, or under an employment agreement.
If the extra pay is not required by the federal FLSA overtime rule, it generally is not qualified overtime compensation for this deduction.
State-Law Overtime
Some states require overtime in situations where federal law does not.
Overtime paid only because of state law, an employer policy, or a collective bargaining agreement is not automatically qualified overtime compensation.
Payroll may need to determine whether any part is creditable toward the employer's federal FLSA overtime obligation.
There can be overlap. A worker may have hours that satisfy both state and federal rules.
Only the amount required under the FLSA qualifies, but the interaction can be more complicated than the label on the pay stub.
Holiday Pay, Shift Differentials, and Bonuses
Extra pay for holidays, nights, weekends, difficult assignments, or attendance is not automatically qualified overtime.
Bonuses and shift differentials may affect the regular-rate calculation, but they are not automatically the deductible overtime premium.
Start with why the amount was paid, not what payroll called it.
The Federal Overtime Rules Matter
For compensation to qualify, the worker generally must be covered by the FLSA and not exempt from its overtime requirement.
Many covered, nonexempt employees must receive at least time and a half after working more than 40 hours in a workweek.
But the FLSA contains exemptions and special rules based on job duties, employer type, industry, and the work performed.
A job title alone does not always answer the question.
Being paid a salary also does not automatically settle it.
Some salaried workers are nonexempt and can receive federally required overtime. Other employees are exempt and may receive extra pay under a company plan without receiving qualified overtime for this deduction.
Special rules can apply to law enforcement, firefighters, health care workers, federal employees, transportation workers, agriculture, and other industries.
The Department of Labor’s Fair Labor Standards Act guide is a useful starting point.
The Department of Labor generally handles FLSA coverage questions. The IRS handles the tax deduction.
When the worker’s exemption status is unclear, both sides may need review.
Where Qualified Overtime Appears on Form W-2
The reporting rules changed after the special transition year of 2025.
For tax year 2026, employers generally must separately report qualified overtime compensation on Form W-2 in box 12 using code TT.
The amount does not represent all overtime wages.
Code TT reports the total qualified overtime compensation paid.
Your final deduction may be lower because the annual limit and income phaseout are applied on your tax return.
The 2026 Form W-2 reporting instructions provide the current employer rules.
When your W-2 arrives, compare the code TT amount with your final pay stub and year-end payroll summary.
Do not compare it with total overtime pay and assume the difference is an error.
Remember that the deductible portion may be only the premium above the regular rate.
If the amount still looks wrong, ask payroll how it was calculated.
Should You Change Form W-4?
Maybe, but do not make the decision from one overtime check.
Use the IRS Tax Withholding Estimator with recent pay stubs and information about the rest of the household.
The estimator has been updated to account for the qualified overtime deduction.
Then decide whether a new Form W-4 makes sense. IRSProb’s guide can also help you review your 2026 tax withholding .
Do not claim that you are exempt from withholding simply because you work overtime.
Exempt status has separate requirements.
A poorly planned change can leave you owing tax and possibly an underpayment penalty.
What to Do if the Reported Amount Looks Wrong
Start with records, not accusations.
- Gather your pay stubs and year-end payroll summary.
- Identify your regular rate and overtime rate.
- Separate total overtime-hour pay from the overtime premium.
- Ask payroll whether the overtime was required under the FLSA.
- Compare the result with Form W-2, box 12, code TT.
- Request Form W-2c if the employer confirms that code TT is wrong.
- Keep the explanation and corrected documents with your tax records.
If qualified overtime is omitted or understated in box 12, code TT, ask the employer for Form W-2c.
IRS guidance says an employee generally cannot use an omitted amount to calculate the deduction unless it is properly reported on the corrected W-2.
Form 4852 does not replace this reporting requirement.
If code TT is overstated, use only the qualified overtime actually paid.
Do not invent an amount because you think the W-2 is too low.
Multiple jobs, side income, or a spouse's earnings can also explain why a regular job can still leave you owing taxes .
What Matters Most
Taxes coming out of an overtime check do not automatically mean payroll is wrong.
The deduction may appear on your federal return rather than as completely tax-free pay.
Only the qualified premium above your regular rate may count.
Social Security and Medicare taxes generally remain, and extra pay required only by company policy or state law may not qualify.
Start with the pay stub. Check the federal overtime rule. Follow the qualified amount to Form W-2. Then review the entire tax return before changing withholding.
The goal is not to chase a slogan. The goal is to claim the deduction you are actually allowed without creating another tax problem.
Thinking about changing your withholding because of overtime?
Review your pay stubs, qualified overtime amount, Form W-2 reporting, and the rest of your household income before making a change.
Review Your 2026 Tax WithholdingFrequently Asked Questions
Is All Overtime Pay Tax-Free?
No. The deduction generally applies only to qualified overtime compensation above the regular rate, subject to federal overtime rules, annual limits, and the income phaseout.
Why Is Federal Income Tax Still Withheld?
Qualified overtime generally remains wages for withholding. The deduction is claimed on the federal return unless the expected benefit is properly reflected through an updated Form W-4.
Do Social Security and Medicare Taxes Still Apply?
Generally, yes. The overtime deduction does not normally remove qualified overtime from Social Security or Medicare wages.
Does Overtime Required Only by State Law Qualify?
Not automatically. Payroll may need to determine whether part of the payment satisfies the federal FLSA overtime obligation. Only the federally required amount qualifies.
Can a Salaried Employee Claim the Deduction?
Possibly. Salary alone does not decide FLSA status. The employee must receive qualified overtime required under the federal law and meet the tax requirements.
Where Is Qualified Overtime Reported on Form W-2?
For 2026, employers generally report total qualified overtime paid in box 12 using code TT. The final deduction may be lower after limits and the income phaseout.
Will the Deduction Automatically Increase My Refund?
No. It can reduce taxable income, but your refund depends on the complete return, including income, withholding, credits, deductions, and payments.